Find Out How Much You Could Borrow
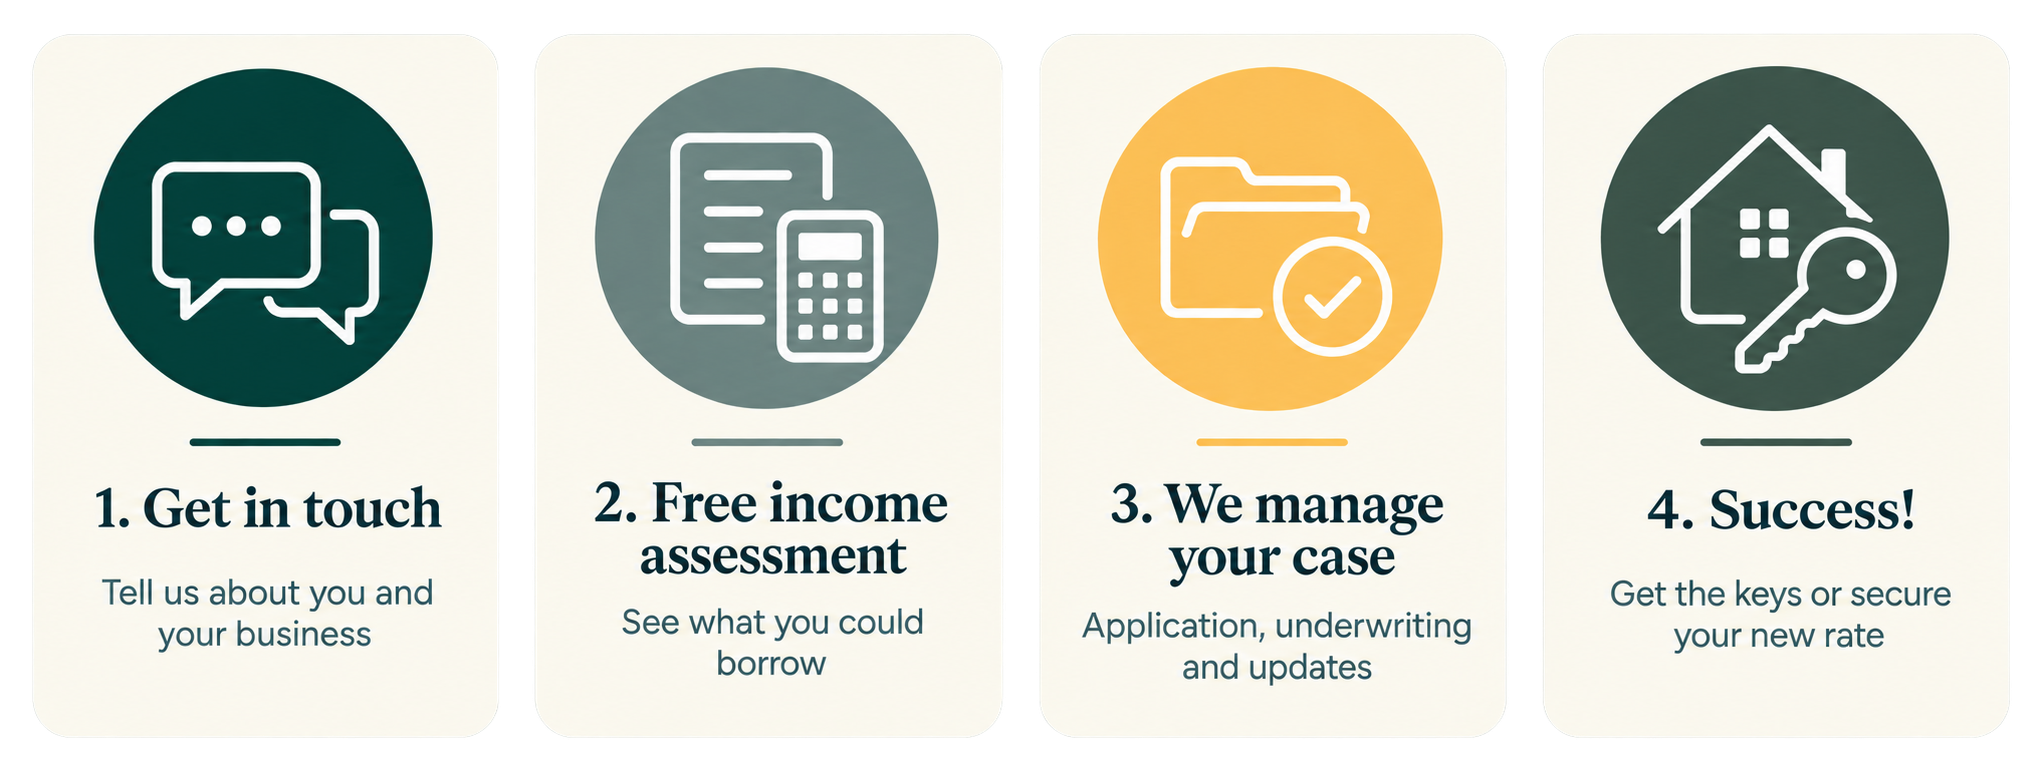
Leave your details and we'll call you back to go through how you pay yourself, and tell you how much you could borrow
Mortgages For Company Directors Who Don’t Want A Bigger Tax Bill
Borrow more based on what your business earns, not just what you draw.
When your income doesn't fit the form, the mortgage doesn't fit either.
You’ve worked hard over the years to build a strong business. It's profitable, business levels are good and you’ve been able to provide well for yourself and your family. Then your dream home comes onto the market but, because of how your income has been assessed, the bank says no and the process is hanging in the balance. You now face either losing your dream property or suffering the financial repercussions of drawing more money from the business and increasing your tax bill. That’s stress you do not need to add to your already busy lifestyle.
Whether you are purchasing a home or changing lender, the problem is that all lenders assess income differently and most lenders have processes geared to favour employed applicants. This makes it harder for the self-employed, particularly company directors, to have their income assessed in a way that maximises borrowing and doesn’t penalise tax efficiency.
If that’s happened to you, you will know the frustration of the back and forth between lenders and the very real possibility of losing your dream home, or switching to an uncompetitive rate through no fault of your own.
But it doesn’t need to be that way and here’s why.
At JFinance, we have over 25 years’ experience with self-employed applicants and the weird and wonderful ways of structuring income - we’ve seen it all!
We have access to over 100 lenders and have great working relationships with them, so we can ensure your case is presented at its best and fully understood from the get-go, using salary and dividends or even your profits. This increases your chances of being accepted, and smooths the mortgage journey as much as possible.
But our service doesn’t end there, we continue to be a lifeline and support throughout the process, to lend an ear or get involved if things go awry.
To explore your options today, fill in our quick enquiry form and leave the rest to us!
Experience Matters
We have been advising clients for over 25 years, and in that time we have seen almost every kind of mortgage scenario there is. That depth of experience means we are rarely surprised by a complicated case, and we know which lenders are genuinely flexible versus which only claim to be. You benefit from decades of pattern recognition, not guesswork.
Whole of Market
As a whole-of-market broker, we have access to over 100 lenders, including many that don't deal directly with the public. We're not tied to any one institution's products; we take time to understand your circumstances and match you with the lender whose criteria genuinely fit your situation.
Experts in Complex Income Structures
Every applicant's income looks different, and a standard payslip is often just one part of the picture. We regularly work with self-employed applicants, contractors, directors and those with multiple income streams, building a case that presents your full circumstances clearly to lenders, so you get a 'yes'.
Right Lender First Time
A declined application can sit on your credit file and make the next lender more cautious. Our experience means we understand how individual underwriters interpret criteria, so we can steer you toward lenders who are genuinely likely to say yes, reducing wasted applications and unnecessary stress.